The Labor Department announced a new independent-contractor rule on November 19 that gives greater weight to control over work and opportunities for business profit or loss. The distinction affects federal minimum-wage and overtime protections, which apply to covered, nonexempt employees.
The announcement does not start the new standard immediately. The department says it will take effect 60 days after Federal Register publication. Its posted final-rule document still contains a placeholder for that publication-based effective date and says it is awaiting placement on public inspection. An exact calendar deadline cannot be calculated from the announcement date alone.
What changes in the federal test
The rule replaces the department's 2024 regulations with an approach similar to its 2021 framework. It also applies the analysis to the Family and Medical Leave Act and Migrant and Seasonal Agricultural Worker Protection Act, which use the same statutory definition of employment.
The central question remains whether someone operates an independent business or depends economically on an employer for work. Two factors carry particular weight: who controls the work, and whether the worker can make business decisions or investments that create opportunities for profit or loss.
Three other factors concern skills, the relationship's permanence and whether the work belongs to an integrated production process. Actual working practices carry more significance than independence promised on paper.
Employment lawyers Jim Paretti, Alex MacDonald and Rob Pritchard at Littler describe the change as a move away from the 2024 rule's unweighted multifactor approach. They also caution that courts determine whether a classification is correct. An independent-contractor agreement does not settle that question by itself.
Control means practical choices
The department's new fact sheet examines scheduling, project selection and the ability to work for other businesses. A worker's practical freedom in those areas can point toward independent contracting. An employer's substantial control can point toward employment.
The profit test examines initiative and management of investments. Earning more by working longer or faster generally points toward employee status. Business decisions that affect earnings can point toward independent contracting.
When both core factors support the same classification, the department says they will usually outweigh the remaining factors. Its fact sheet still says no single factor determines status.
Why delivery and trucking examples differ
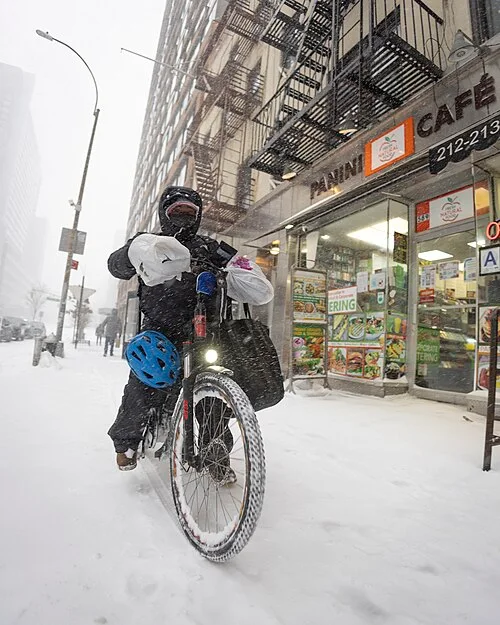
The department's hypothetical examples compare delivery-app arrangements. A platform that withholds useful order information, penalizes rejected offers and makes working for competing apps impractical exercises control pointing toward employment.
Another scenario allows informed delivery choices, rejection without penalty and work for competing services. That arrangement points toward contracting under the control factor. Location monitoring and penalties for repeatedly canceling already accepted deliveries do not alone reverse that conclusion in the agency's example.
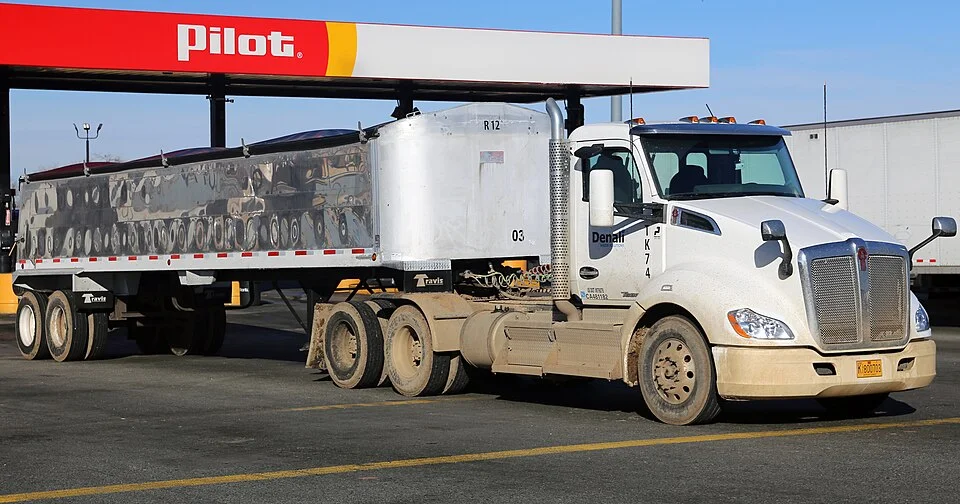
Its trucking examples distinguish a meaningful investment from the cost of obtaining work. A driver who cannot negotiate undisclosed shipment rates and has no realistic path to owning a leased truck lacks the business opportunity described in the contractor test. Negotiable rates, return-load opportunities and a realistic ownership path support the opposite conclusion under that factor.
These examples analyze particular factors under stated facts. They do not classify every courier or truck driver.
State law and tax rules remain separate
The department says this rule does not preempt state or local laws or change classification under other federal statutes, including the Internal Revenue Code.
California's Labor Commissioner's guidance, for example, describes an ABC test requiring freedom from control, work outside the hiring entity's usual business and an independently established business. All three conditions must be satisfied where that test applies. The state also lists exceptions and different tests for particular occupations and relationships.
That produces a separate question for a business operating across state lines: which state rules govern the work, and does an exception apply? Meeting the new federal factors alone does not answer it.
For federal employment taxes, the IRS considers behavioral control, financial control and the parties' relationship. It says there is no fixed number of factors that makes someone an employee or contractor. A worker or business uncertain about federal tax status can request an IRS determination using Form SS-8; the agency says that process can take at least six months.